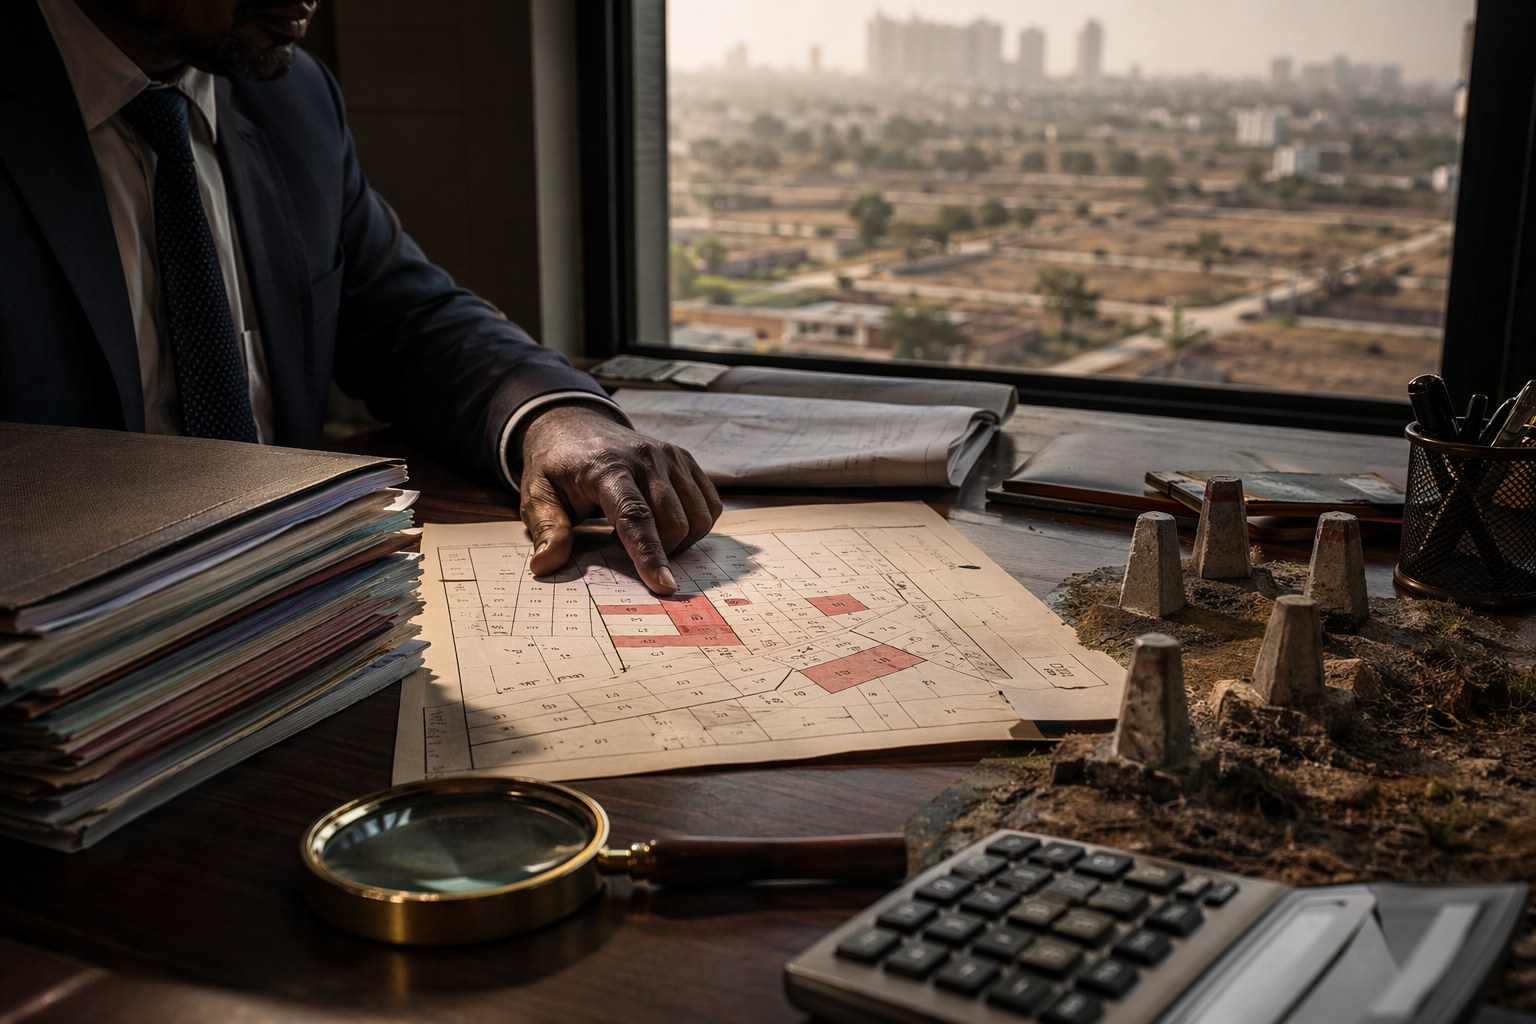
Telangana Lenders Tighten Plot Loan Pricing Over 22-A Risk is becoming a serious talking point in Hyderabad’s land market, especially for open plots around growth corridors. As per latest IGRS data, Telangana has 3,076,153 prohibited properties under Section 22-A. That single number is enough to make banks, NBFCs and housing finance companies look harder at plot loan files before sanction, especially where title chains, survey numbers and Dharani records do not match cleanly.
In our experience, flat loans move faster because the project approvals, RERA record and builder documents are usually packaged. Plot loans are different. The lender depends heavily on survey number, village record, pahani, EC, mutation status, SRO record and whether the land falls under any prohibited category. When Section 22-A risk is large, lenders naturally price that uncertainty into margins, disbursal conditions and legal scrutiny.
Telangana Lenders Tighten Plot Loan Pricing: What Is Changing For Buyers?
The immediate change is not always a public interest rate revision. Many times, it shows up quietly inside the loan file. A buyer may get a lower loan-to-value, extra legal opinion requirement, insistence on original link documents, or delayed disbursal until the SRO and Dharani trail is verified. In some cases, the lender may simply say the plot is not acceptable as security.
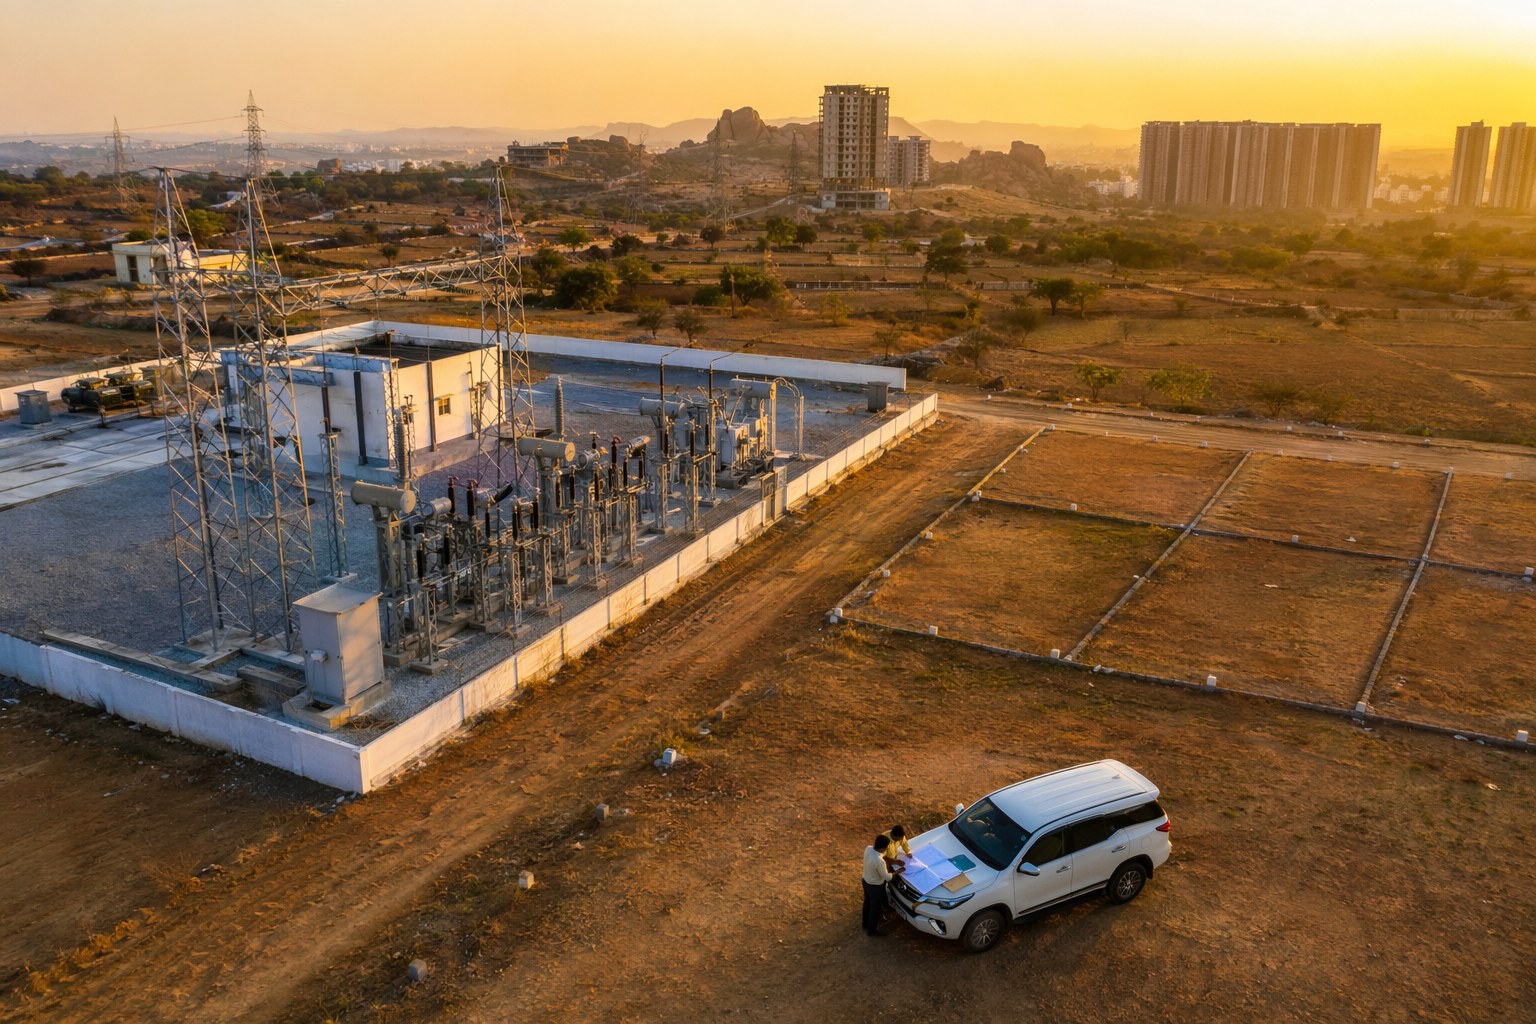
This matters most in Hyderabad’s active land belts: Mokila and Shankarpally mandal, Kollur and Tellapur side, Narsingi and Gandipet mandal, Adibatla and Ibrahimpatnam mandal, Maheshwaram, Tukkuguda, Shadnagar, Patancheru and Sangareddy stretches. These locations see regular buyer interest from IT employees, NRIs and investors. But the same growth story also brings conversion issues, old assignments, missing link documents, layout approval doubts and survey boundary disputes.
Our view is simple: a plot with unclear title is not just a buyer’s risk. It becomes a lender’s collateral risk. That is why 22-A checking is moving from a formality to a front-line credit filter.
Before paying token advance, buyers should run a basic screen using the Section 22-A Prohibited Property Check, verify the survey number through the Survey Number Finder, and pull the latest transaction trail using the Encumbrance Certificate Search. These checks do not replace a lawyer, but they can save a buyer from entering a bad negotiation.
Telangana Lenders Tighten Plot Loan Pricing Because 22-A Is A Title Risk, Not A Small Technical Issue
Section 22-A properties are prohibited from registration under specified categories. The problem for lenders is that the risk may not be visible from a glossy layout brochure or a broker’s WhatsApp location pin. It sits in government records, old village files, SRO entries, assignment history and revenue classifications.
A land parcel may look normal on the ground. There may be roads, compound walls and neighbouring houses. Still, if the survey number has a prohibited flag, the bank’s legal team will hesitate. If the bank cannot register a valid mortgage or enforce security cleanly, the loan becomes uncomfortable.
For buyers, this can create three practical issues:
- Approval may take longer: The bank may ask for extra legal reports, revenue certificates or clarification from the seller.
- Margin money may increase: Even if the loan is approved, the lender may fund a smaller portion of the transaction value.
- Disbursal may be conditional: Funds may be released only after registration, mortgage creation and document deposit are completed to the lender’s satisfaction.
In Hyderabad’s plot market, this is especially relevant for old gram panchayat layouts, unapproved subdivisions, inherited land, assigned land, lands near water bodies, and parcels where the village name, survey number or extent differs across documents.
Where Hyderabad Plot Buyers Should Be Extra Careful
Not every plot in a fast-growing mandal is risky. But certain situations deserve slower due diligence. We have seen buyers get excited by location names such as Kokapet, Mokila, Kollur, Tellapur, Adibatla or Shadnagar, while the actual land record belongs to a different village, different mandal jurisdiction or a survey number with complications.
For example, a broker may market a plot as “near Kokapet”, but the revenue village and SRO jurisdiction may tell a more precise story. The same applies around ORR exits, proposed road corridors and villa-layout belts. A lender will not sanction based on branding. It will check title, SRO jurisdiction, market value, EC and mortgageability.
Buyers should also compare the declared value and government guideline value before budgeting stamp duty and registration expenses. Use the Market Value / Guideline Value Search and Stamp Duty Calculator before finalising the sale consideration. If the plot is part of a larger development, the RERA Project Lookup is useful where RERA registration applies.
How Lenders May Rework Plot Loan Conditions
Plot loans are already treated differently from home loans because land is harder to value and easier to dispute. With a large 22-A base in the state records, lenders may become stricter in four areas.
| Loan File Area | Likely Lender Response | Buyer Impact |
|---|---|---|
| Legal verification | More checks on link documents, pahani, Dharani status and SRO record | Longer processing time |
| Property eligibility | Rejection if survey number shows prohibited or unclear status | Buyer may need to change property |
| Funding margin | Lower comfort on high-risk land parcels | Higher own contribution may be needed |
| Disbursal | Release linked to clean registration and mortgage creation | Seller payment timelines may change |
From a lender’s side, this is not over-caution. A bank wants enforceable security. If the plot later faces registration refusal, title dispute or government restriction, recovery becomes difficult. For a buyer, the same issue can block resale, construction loan conversion or future mortgage.
What Sellers And Developers Should Expect
Sellers in peripheral Hyderabad markets should keep documents ready before bringing land to market. A serious buyer with bank funding will ask for more than a copy of the sale deed. Expect requests for link documents, EC, latest market value check, mutation proof, layout approval, land conversion papers where relevant, and clarity on the exact survey number.
Developers selling plotted layouts in mandals such as Shankarpally, Maheshwaram, Ibrahimpatnam, Kandukur and Patancheru should also expect buyers to ask about SRO jurisdiction and road access. The Find Your SRO Office, SRO Village Directory and Property Verification Tool can help buyers cross-check basic details before legal review.
In my opinion, clean-title sellers will benefit from this stricter lending mood. When banks become choosy, plots with proper records, clear EC, correct survey boundaries and acceptable approvals stand out. They may not need loud marketing. The documents will do half the selling.
Buyer Checklist Before Applying For A Plot Loan
If you are buying a plot in Telangana with bank finance, finish these checks before loan login. It is better to lose a token advance discussion than get stuck after sanction.
- Check whether the survey number appears in prohibited property records.
- Match village, mandal, extent and boundaries across sale deed, pahani, EC and layout documents.
- Verify SRO jurisdiction and latest guideline value.
- Ask for the full link document chain, not only the current owner’s deed.
- Check whether any mortgage, court case or charge appears in EC or lender records.
- Confirm layout approval status and road access before paying a major advance.
- Keep enough time in the sale agreement for lender legal verification.
The key message is not that buyers should avoid plots. Telangana land remains a preferred asset for many families. But the days of buying only on location buzz are risky. When the state has 3,076,153 prohibited properties in IGRS data, every serious plot buyer must treat title verification as part of price negotiation.
Frequently Asked Questions
Why are Telangana lenders tightening plot loan pricing over 22-A risk?
Lenders are cautious because Section 22-A can affect registration and mortgageability. If a plot cannot be cleanly registered or enforced as security, the bank may reduce funding, delay disbursal or reject the property.
How many prohibited properties are recorded in Telangana?
As per latest IGRS data available in our database, Telangana has 3,076,153 prohibited properties under Section 22-A.
Can I get a plot loan if the survey number has a 22-A issue?
Usually, it becomes difficult. The lender’s legal team will examine the exact nature of the entry. If the property is not acceptable as mortgage security, the loan may not be sanctioned.
Which checks should I do before paying advance for a Hyderabad plot?
Check Section 22-A status, EC, survey number, SRO jurisdiction, guideline value, link documents, layout approval and road access. A local property lawyer should review the final file before registration.
Does a clear EC mean the plot is fully safe?
No. EC is only one part of due diligence. You should also check Dharani/revenue records, pahani, prohibited property status, layout approval, mutation and the full link document chain.