Telangana 22-A Tags Put Mortgage Securitisation in Focus as lenders, trustees and investors take a closer look at title risk in property-backed loans. Telangana has 147,934 properties listed under Section 22-A prohibited properties, a number large enough to matter not only for individual buyers, but also for banks, NBFCs and mortgage pool buyers. If a mortgaged property later turns out to be restricted for registration, the security value can fall sharply and the loan may become difficult to enforce.
For Hyderabad’s active credit market, this is not a small back-office issue. Home loans, loan-against-property portfolios and developer receivables are increasingly packaged into securitised pools. Investors buying these pools expect clean collateral, clear encumbrance history and predictable recovery routes. A 22-A tag can disturb all three.
Telangana 22-A Tags and why lenders are watching mortgage pools
Section 22-A properties are those where registration is prohibited or restricted under state records. These may include government lands, assigned lands, endowment lands, wakf-related entries, ceiling surplus lands, disputed survey numbers and other categories notified to the registration department. Once a property is flagged, the Sub-Registrar Office may refuse registration of sale, gift, mortgage release or transfer, depending on the nature of the entry.
In a normal retail home loan, the bank checks link documents, EC, tax receipts, building permission and valuation. But securitisation adds one more layer. The loan is not sitting only on one bank’s book. It may be transferred into a pool, sold to investors through pass-through certificates, or assigned to another lender. That means one weak title can travel from branch file to capital market product.
In our experience, the biggest risk is not always fraud. Many times, it is an old survey number entry, a missed pahani check, or a land parcel that changed hands multiple times before the 22-A listing became visible to the buyer.
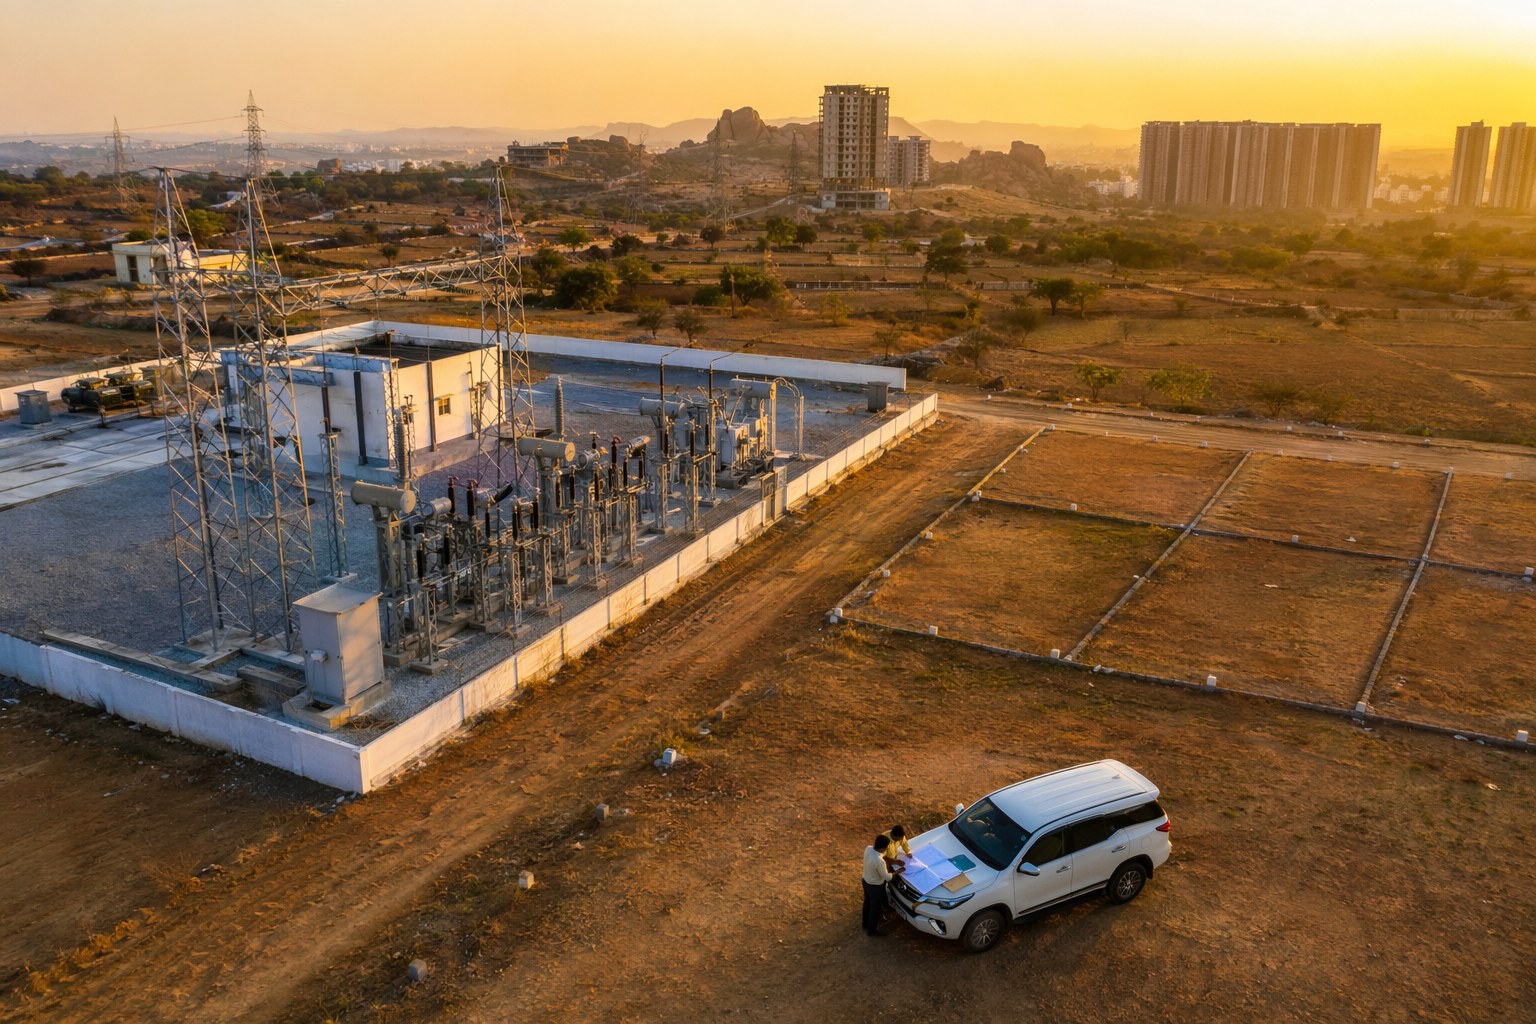
For properties in and around Hyderabad, the issue becomes sharper because land values are high. In Kokapet-Neopolis, HMDA auction prices have crossed ₹100 crore per acre in the past. In Mokila, auction bids touched around ₹1 lakh per square yard. Even in fast-growing belts like Patancheru, Gandipet, Shankarpally, Medchal and Hayathnagar, a title defect can change the economics of a secured loan overnight.
Telangana 22-A Tags can affect due diligence at three levels
The 147,934 prohibited-property base pushes lenders to look beyond standard valuation reports. A bank may have a sanctioned home loan with an acceptable loan-to-value ratio, but if the underlying survey number has a 22-A entry, the collateral may not be freely saleable. That affects both recovery value and investor confidence.
| Due diligence layer | What can go wrong | Why it matters for securitisation |
|---|---|---|
| Title and survey number | Property falls in a prohibited survey number or assigned land record | Collateral may be hard to transfer or auction |
| Registration history | Old sale deeds exist, but latest SRO system blocks future registration | Pool buyer may demand exclusion or higher credit support |
| Encumbrance and mortgage | Mortgage created without full land classification check | Security enforcement may face objections |
| Valuation | Market rate assumed without checking legal saleability | Loan-to-value becomes misleading |
Before funding or pooling a loan, lenders should run a direct Section 22-A Prohibited Property Check, not just depend on photocopies given by the borrower. The Encumbrance Certificate Search is also needed, but EC alone will not prove that the property is outside 22-A. EC shows registered transactions; it does not always answer land classification questions.
For land parcels, especially in village layouts and peripheral mandals, the survey number must be matched carefully. A plot buyer in Shankarpally mandal or Abdullapurmet mandal may have a layout number and plot number, but the lender must trace it back to the parent survey number. The Survey Number Finder and Property Verification Tool can reduce this gap at the first screening stage.
What this means for mortgage securitisation quality
Mortgage securitisation depends on predictability. Investors want to know that if borrowers default, the asset can be enforced, sold and recovered without years of title litigation. A 22-A tag creates uncertainty on three fronts: legal transfer, valuation and recovery timeline.
Take a loan-against-property pool with mixed collateral from Serilingampally, Uppal, Manikonda, Bachupally and Shamshabad. The urban apartment loans may have clear RERA and society records. But a few high-ticket land-backed loans in Gandipet or Maheshwaram could carry survey-level risk. If those loans are large, even a small number of defective titles can disturb pool performance.
Investors may react in practical ways:
- Ask for loan-level 22-A checks before buying pools.
- Exclude land-backed loans where pahanis, dharani entries and SRO records do not match.
- Demand higher credit enhancement from the originator.
- Seek stronger representations and warranties on title.
- Apply valuation haircuts to collateral in high-risk mandals.
This will not stop mortgage securitisation in Telangana. But it can make pool selection more selective. Clean home loan pools from completed RERA projects may be priced better than mixed collateral pools with agricultural land conversions, gram panchayat layouts or old unapproved plots.
Hyderabad localities where title screening becomes more sensitive
The risk is not equal across the city. Fully built apartment markets like Madhapur, Kondapur, Gachibowli, Nallagandla and Kukatpally generally have clearer project-level documentation, though every flat still needs checks. The harder cases usually come from land, villas, plotted layouts and older conversion properties.
In the western corridor, Kokapet, Narsingi, Manikonda, Puppalaguda, Tellapur and Mokila have seen strong price growth. High values attract credit, but they also magnify title risk. A single disputed acre in Gandipet mandal can support several crores of borrowing. If that acre is later questioned under 22-A records, the lender’s collateral cover becomes doubtful.
On the northern side, Medchal, Shamirpet, Kompally, Dundigal and Turkapally have many plotted and warehouse-linked transactions. In the east, Hayathnagar, Abdullapurmet, Ghatkesar and Yadagirigutta belt attract investors looking for land appreciation. In the south, Shamshabad, Maheshwaram, Tukkuguda and Kandukur continue to see airport and pharma-city related interest. These are exactly the places where survey number verification, land use and registration status should be checked before a loan file moves to sanction.
Borrowers and lenders can also verify the relevant registration jurisdiction through Find Your SRO Office. For pricing and stamp duty assumptions, the Market Value / Guideline Value Search and Stamp Duty Calculator are useful, but they must sit alongside title checks. A ready reckoner value does not clean a bad title.
How originators can protect investor confidence
For banks and NBFCs, the fix is not complicated, but it has to be disciplined. First, collect property identifiers properly: district, mandal, village, survey number, sub-division, plot number, flat number and SRO. Second, match borrower documents with dharani, pahani, layout permission, building permission and EC records. Third, mark loans with title exceptions before they enter any securitised pool.
Originators should create a separate risk bucket for properties that are not directly under 22-A but have nearby survey number confusion. We have seen cases where one digit in the survey number changes the entire legal position. In high-value areas, that small error can become a multi-crore recovery problem.
For apartment collateral, RERA verification is equally useful. The RERA Project Lookup helps lenders and buyers check project registration details. For land-backed developer finance, teams should also look at zoning through tools like Land Use Zone Finder, especially in HMDA and surrounding gram panchayat areas.
Trustees and rating teams may now ask sharper questions: How many loans in the pool are land-backed? How many are from non-municipal areas? Were 22-A checks done at sanction date or only at pooling date? Is there indemnity if a property later appears in the prohibited list? These questions are fair. Investor confidence improves when the originator can answer them with documents, not verbal comfort.
Telangana 22-A Tags are now a credit market issue, not only a buyer issue
For years, 22-A was discussed mainly as a registration headache for individual buyers. That view is too narrow now. With 147,934 prohibited properties on record, the issue has entered the credit chain. It affects how banks value collateral, how NBFCs structure loan-against-property products, and how investors price mortgage-backed exposure.
My view is simple: Telangana’s real estate market remains strong, especially around Hyderabad, but title discipline has to catch up with price growth. When land in premium corridors trades at auction-discovered rates of ₹70 crore to ₹100 crore per acre, casual due diligence is not acceptable. Lenders who clean their collateral data early will get better pool quality and stronger investor trust. Those who treat 22-A as a last-minute SRO issue may face painful surprises during assignment, securitisation or recovery.
For buyers also, the lesson is direct. Before paying token advance on any plot, villa land or old property, check 22-A status, EC, SRO jurisdiction and survey records. In Telangana, a good location is valuable only when the title can be registered and enforced.
Frequently Asked Questions
What are Telangana 22-A tags?
Telangana 22-A tags refer to properties listed as prohibited or restricted for registration under Section 22-A. These may include government land, assigned land, endowment land, wakf entries, ceiling surplus land and other notified categories.
Why do 22-A properties matter for mortgage securitisation?
If a mortgaged property is later found to be under 22-A, the lender may struggle to sell or enforce the security. In a securitised mortgage pool, that weakens collateral quality and can reduce investor confidence.
Is an Encumbrance Certificate enough to clear 22-A risk?
No. An EC shows registered transactions and mortgages, but it may not fully confirm land classification or prohibited-property status. A separate 22-A check and survey number verification are needed.
Which Hyderabad areas need extra title checks?
Land and plotted layout markets in Gandipet, Shankarpally, Mokila, Maheshwaram, Shamshabad, Medchal, Shamirpet, Hayathnagar and Abdullapurmet need careful survey number and SRO-level verification.
How can a buyer check if a property is safe?
Start with a Section 22-A check, EC search, survey number verification, SRO identification and guideline value review. For apartments, also check the project on RERA before paying any advance.