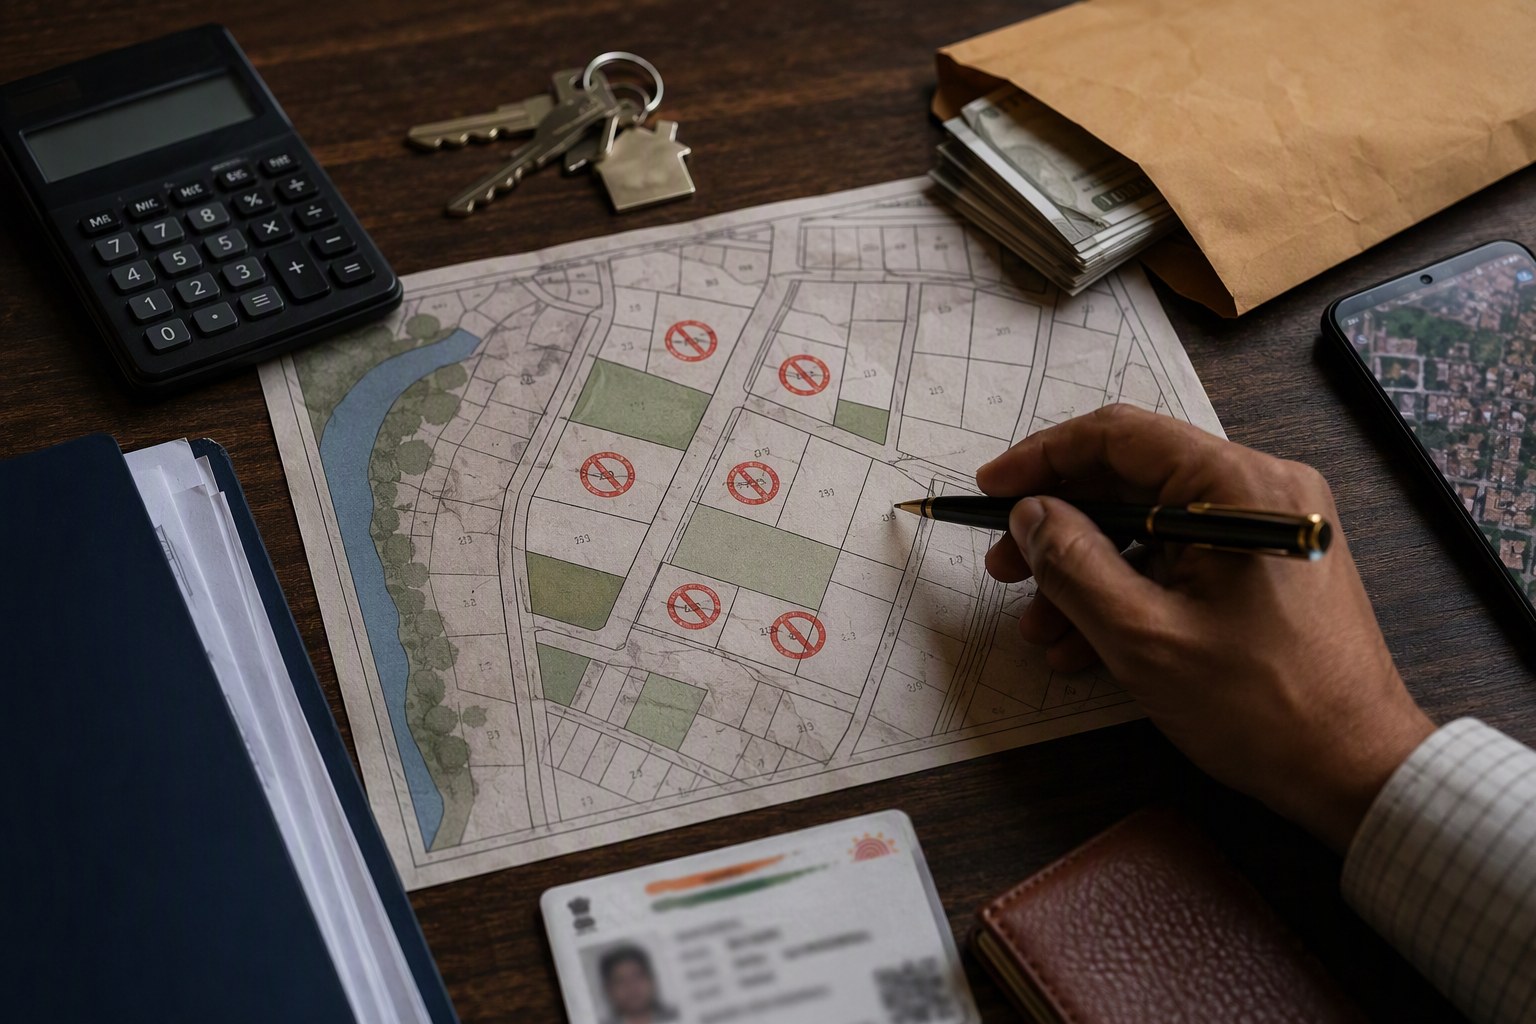
Telangana Investors Recheck JV Land Before Funding Projects because the first risk in a joint development is no longer only construction cost or sales velocity. It is the base land record. Across Hyderabad’s growth corridors, investors funding joint development agreements, landowner-share projects and early-stage approvals are asking one hard question before the first cheque: is this land clean on Dharani, EC, pahani and Section 22-A lists?
The trigger is visible in the numbers. Telangana has 147,934 prohibited property entries under Section 22-A. For a project investor, that is not a small back-office statistic. One missed prohibited entry can delay registration, block a mortgage, weaken RERA disclosures, disturb HMDA or municipal approvals, and reduce exit value when the project is sold to homebuyers, NBFCs, PE funds or another developer.
Our view is simple: in a JV, the land is the promoter’s real balance sheet. If the land record is shaky, even a good location and a strong sales brochure cannot protect the investor.
In the last two years, Hyderabad has seen aggressive land pricing in Kokapet, Neopolis, Narsingi, Tellapur, Kollur, Mokila, Shankarpally, Patancheru, Adibatla and Maheshwaram. When the underlying land costs ₹8 crore to ₹20 crore per acre in many private market conversations, and auction benchmarks have touched far higher levels, a title defect is not a minor legal issue. It directly affects project finance, launch timing and the price at which investors can exit.
Why Telangana Investors Recheck JV Land Before Funding Projects Now
The new caution is not fear for the sake of fear. It is practical. Telangana’s land market has become faster than the paperwork behind many parcels. Developers are signing term sheets based on location, road access, sharing ratio and saleable area. Investors are now slowing that first step and asking for the survey number trail before accepting any projection.
Take the western corridor. In Gandipet mandal, Kokapet and Narsingi have become high-value apartment and office-linked locations. HMDA’s Kokapet Neopolis auction in 2023 saw bids touching around ₹100.75 crore per acre, a headline number that changed landowner expectations across nearby villages. Budvel auctions also crossed strong levels, with bids above ₹30 crore per acre in several parcels. These numbers created confidence, but they also pushed more landowners and developers into quick JV negotiations.
Now look at the investor’s problem. A spreadsheet may assume a landowner share of 40% or 45%, an FSI-linked saleable area, and a launch price based on nearby projects. But if one survey number carries a Section 22-A restriction, assigned land issue, government land claim, court stay, wakf/endowment flag, ceiling surplus reference or missing mutation chain, the entire project can slip by months. In some cases, it may need restructuring or exclusion of that parcel.
This is why many funders now use basic tools before meeting the developer. They check the Section 22-A Prohibited Property Check, pull the Encumbrance Certificate Search, verify ready reckoner values through the Market Value / Guideline Value Search, and confirm the correct registration office using Find Your SRO Office. These are not replacements for a lawyer, but they help investors ask sharper questions.
Telangana Investors Recheck JV Land Before Funding Projects Because Approvals Depend On Title
A Hyderabad project does not move from paper to sales only because a landowner signs a development agreement. The land record affects every next step. HMDA layout permission, building permission, RERA registration, bank funding, homebuyer agreements, mortgage creation and final conveyance all depend on the quality of title.
In a JV or joint development agreement, the developer usually brings construction capability, approvals, marketing and execution. The landowner brings land. The investor may fund refundable deposit, approval cost, early civil works, architect fees, liaison expenses or working capital till bookings start. If the land is later found to be prohibited or partly disputed, the investor’s money gets stuck before the project generates sale cash flow.
We have seen this pattern in Hyderabad’s outer growth belt: the first presentation talks about acres, frontage and expected apartment price; the second meeting reveals that some survey numbers are under old family partitions, unregistered agreements, pending succession, or boundary mismatch. By then, soft expenses may already be committed.
| Investor check | Why it matters in a JV project | Common Hyderabad example |
|---|---|---|
| Section 22-A status | Prohibited entries can stop registration and funding | Assigned land, government land, wakf/endowment claims |
| EC for 30 years | Shows mortgages, sales, releases and court attachments | Old bank loan release not reflected before JDA signing |
| Dharani and pahani match | Confirms pattadar, extent and survey details | Owner name differs between old pahani and current Dharani |
| SRO value and market value | Helps test stamp duty, capital structure and land cost | Guideline value far below actual JV valuation in Kokapet or Tellapur |
| Road width and zoning | Impacts FSI, building height and saleable area | Access road not enough for projected high-rise permission |
What Exactly Is The Base Land Record In A Telangana JV?
When investors say they are checking the base land record, they are not referring to one single document. They mean the full land identity of the parcel. For agricultural-origin land, this usually starts with survey number, village, mandal, pattadar name, khata number, extent, nature of land, pahani history, Dharani entry and mutation chain. For converted or urban land, the file should also include layout approvals, conversion orders, link documents, EC, SRO registration trail and municipal records.
In Ranga Reddy, Sangareddy, Medchal-Malkajgiri and Yadadri-Bhuvanagiri districts, the same locality name can create confusion. A buyer may say Kollur, but the project land may fall in a specific village and mandal with different SRO handling. A project marketed as near Tellapur may actually sit in a neighbouring revenue village. This matters because the survey number decides the record, not the brochure name.
Before paying, investors should confirm the survey identity through the Survey Number Finder and then run a broader screening through the Property Verification Tool. If the project is already being advertised, the investor should cross-check it on the RERA Project Lookup. A RERA number is useful, but it is not a magic shield against all title questions. It should be read along with the underlying land file.
Section 22-A Is Not A Small Technical Tag
Section 22-A entries restrict registration of certain properties. In practice, this can include government land, assigned land, endowment or wakf land, ceiling surplus land and other categories notified to the registration department. With 147,934 prohibited property entries in Telangana, any investor funding land-linked projects must treat this as a first-level filter.
The problem is that many JV discussions happen based on landowner confidence. A landowner may have possession. The family may have cultivated the land for years. The village may recognise them as owners. But project finance does not run on local reputation alone. The SRO will look at the prohibited list, document history and registration eligibility. Banks and NBFCs will ask for legal clearance. Homebuyers will demand sale deeds without restrictions.
For investors, the safest approach is to assume nothing. Check the entry. Check the survey number spelling. Check subdivisions. Check if only part of the land is affected. In larger parcels, one problematic bit can force a redesign, revised access plan, or change in land pooling structure.
Local Deal Patterns: Kokapet, Tellapur, Kollur, Mokila And Beyond
The western side of Hyderabad remains the sharpest example of this new discipline. Kokapet and Narsingi in Gandipet mandal are no longer speculative outskirts. They are premium development locations. Tellapur and Osman Nagar near Serilingampally and Ramachandrapuram have strong apartment demand due to the Financial District, Gachibowli and Wipro Circle employment belt. Kollur, Velimela and Mokila attract investors looking at plotted, villa and mid-rise apartment plays.
Landowner expectations in these markets have moved up. In established western micro-markets, private land discussions can run into several crores per acre, while development sharing ratios may become aggressive where the land parcel has good road width and clean approvals. In high-demand apartment corridors, landowner share can move towards 40% to 50% of built-up or saleable area depending on location, approval stage and cash deposit. In villa and plotted development belts, the structure may be different, with revenue share or area share tied to infrastructure cost.
On the southern and eastern sides, Maheshwaram, Tukkuguda, Adibatla, Ibrahimpatnam and parts of Yadadri corridor are seeing early-stage investment linked to ORR access, pharma, aerospace, logistics and future residential demand. These locations are attractive because entry price can be lower than Kokapet or Tellapur. But older land records, assigned land pockets and conversion issues can be more visible in such belts. That is exactly where base-record checking becomes valuable.
North Hyderabad has its own pattern. Medchal, Shamirpet, Kompally and nearby mandals have industrial, warehouse, villa and plotted activity. Some parcels have old layouts, gram panchayat approvals, or conversion gaps. An investor funding a developer in these areas must ask whether the proposed project use matches land use and zoning. The Land Use Zone Finder, Road Width Check and FSI/FAR Calculator are useful early screens before expensive design work begins.
How Telangana Investors Recheck JV Land Before Funding Projects In Practice
A good investor checklist is not complicated. It is disciplined. The first step is to collect the land schedule exactly as proposed in the JDA: district, mandal, village, survey numbers, subdivisions, total extent, boundaries and owner names. Do not accept only the marketing name of the location.
Second, verify the title trail. Ask for link documents for at least 30 years, latest EC, pattadar passbook or Dharani extract, pahanis, mutation proceedings, family partition documents where needed, death and legal heir documents, GPA copies if any, and previous development agreements or sale agreements. If the land was converted, ask for conversion order and receipts.
Third, test registration and value assumptions. Telangana sale registration normally carries around 6% total cost, including stamp duty, transfer duty and registration fee for common sale transactions. If the investor is calculating land deposit, refundable advance, or later buyout of landowner share, the numbers should be checked against guideline value and SRO practice. The Stamp Duty Calculator and Composite Value Calculator help estimate the transaction burden before term-sheet signing.
Fourth, check project feasibility. The land may be clean, but the project may still be weak if road width, zoning, open space requirement, OSR, height restrictions or FSI assumptions are wrong. We have seen proposals where projected saleable area looks attractive until access road reality reduces permissible development. The OSR Calculator can flag open space impact at an early stage.
Fifth, track changes after signing. Land records can change due to court orders, fresh registrations, mortgages, family claims or government updates. Investors putting money in tranches should not rely only on a one-day legal opinion. A periodic check through the Property Change Tracker is a sensible habit, especially before second and third disbursements.
Red Flags Investors Should Not Ignore
- Owner name mismatch: Dharani, pahani, EC and link documents should tell a consistent story. Small spelling variations are common, but ownership mismatch needs explanation.
- Partly missing survey numbers: Developers may present a large parcel, but only some survey numbers are ready for JDA. Funding should be linked to the clean portion only.
- Old GPA-based transactions: GPA history must be read carefully, especially where sale deeds were not completed in time.
- Possession without title: Physical control of land is not enough for project finance.
- Unreleased mortgage: EC may show a bank charge, but release deed may be pending or wrongly indexed.
- Government road or nala impact: Revenue maps and master plan roads can cut into developable area.
- 22-A or court references: Even if the owner says it can be cleared, investor money should wait for written proof.
What This Means For Developers Seeking JV Funding
Developers who want faster funding should prepare the land file before approaching investors. In our experience, a clean digital folder can reduce negotiation friction. It should include survey map, Dharani extract, EC, link documents, tax receipts, conversion orders, landowner KYC, litigation declaration, SRO value, zoning extract, road access proof and draft JDA terms.
Developers should also be transparent about weak points. If one survey number is under mutation, say it. If a family settlement deed is pending, disclose it. If a mortgage release is expected, share the bank letter. Investors can handle disclosed risk. Hidden risk breaks trust.
The market is still hungry for good projects. Hyderabad’s residential demand has not disappeared. But funders have become sharper after seeing delays in approvals, RERA registration and cash-flow cycles. A developer with a clean land record will command better terms than one selling only location hype.
Our Opinion: The Smart Money Is Moving From Location-First To Title-First
For many years, Hyderabad real estate rewarded those who entered the right corridor early. That is still true. But in JV funding, the smarter money is now title-first. Location can create upside; title protects capital.
A plot near ORR, a land parcel close to the Financial District, or a villa site in Mokila may look attractive. But if the base land record is not clean, the investor is funding uncertainty. The loss is not only legal fees. It can be lost launch season, delayed approvals, higher interest cost, reduced buyer confidence and weaker exit valuation.
My practical advice to investors is clear: do not release money only on the basis of a signed JDA draft, beautiful elevation, or a famous locality name. Start with survey number, Section 22-A check, EC, Dharani, SRO and zoning. Then discuss FSI, pricing and returns. That order saves capital.
Telangana’s project funding market is maturing. The investors who build this discipline now will avoid many expensive surprises later.
Frequently Asked Questions
Why are Telangana investors checking JV land records before funding?
Because the base land record affects registration, approvals, RERA, bank funding and exit value. A Section 22-A entry, title gap or EC issue can delay the project before sales begin.
What is Section 22-A in Telangana property checks?
Section 22-A refers to prohibited properties where registration may be restricted. Telangana has 147,934 such entries, so investors should check the survey number before funding any land-linked project.
Is a RERA number enough to prove that JV land is safe?
No. RERA registration is useful, but investors should still verify EC, Dharani, pahani, link documents, SRO status, zoning and Section 22-A records.
Which Hyderabad localities need extra caution in JV funding?
High-growth areas like Kokapet, Narsingi, Tellapur, Kollur, Mokila, Shankarpally, Maheshwaram, Adibatla, Medchal and Shamirpet need careful checks because land values and deal sizes are high.
What should an investor check before releasing the first tranche?
Check survey numbers, Dharani, pahani, 30-year EC, Section 22-A status, SRO value, conversion orders, road width, zoning, owner KYC and draft JDA terms.