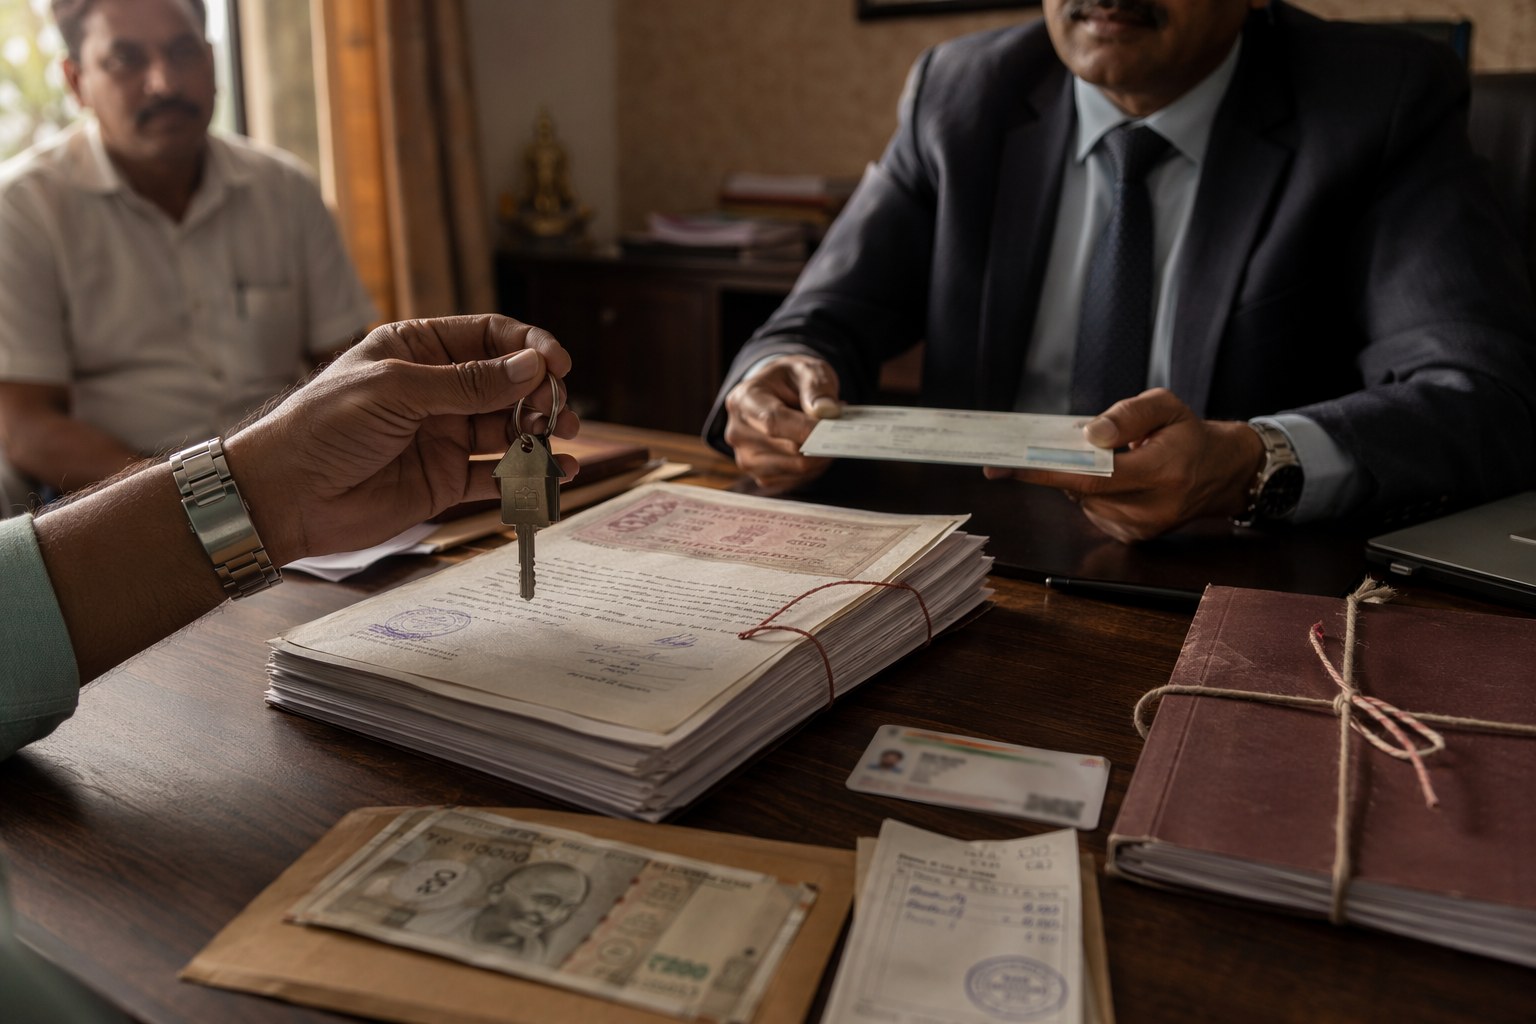
At the SRO office in Serilingampally, a buyer from Kondapur was ready with the seller, witnesses, challans and the sale deed. The token was called. Then came the shock: the bank’s final loan amount was not yet in the seller’s account. The buyer thought the sanction letter meant the full money was guaranteed before signing. The banker quietly said the last tranche would move only after registration and a few checks. This is exactly why banks hold back final disbursement until registration, especially in Telangana property transactions where title, EC, CERSAI and Section 22-A checks can still throw up surprises.
We have seen this confusion in Hyderabad many times — flats in Gachibowli, resale apartments in Kukatpally, plots in Mokila, villas near Narsingi, even standalone houses in Uppal. Buyers assume bank loan disbursement is one single event. In reality, it is a chain of approvals. Sanction is one stage. Legal clearance is another. Technical valuation is another. Final disbursement, particularly the last amount, is tied to the bank’s comfort that the property is now legally registered and mortgageable.
Short answer: banks hold back the final amount because they want proof that ownership has legally moved to the borrower and that the bank can create a valid mortgage after registration.
Why Banks Hold Back Final Disbursement Until Registration in Telangana
The bank is not only funding your home. It is also taking that same property as security. Until registration happens, the buyer does not have final ownership on record. The sale agreement may be signed, the loan may be sanctioned, the property may be physically ready, but the bank still cannot treat the borrower as the registered owner.
That is the heart of the issue. A housing loan is not like a personal loan. The bank wants a clean, enforceable charge over the property. For that, the registered sale deed, updated encumbrance position, original link documents, builder NOC where applicable and mortgage creation formalities must align.
In Telangana, this becomes even more sensitive because property records are spread across registration records, municipal approvals, RERA data for projects, Dharani or revenue records for land, pahani extracts in some rural belts, and CERSAI entries for existing mortgages. A flat in Madhapur may be checked differently from an open plot in Shankarpally mandal. A HMDA layout plot in Bachupally will not be treated like an agricultural land parcel near Shamirpet.
Before you reach the registration office, use basic checks yourself. Start with the Encumbrance Certificate Search, verify government market value through the Market Value / Guideline Value Search, and calculate likely registration costs using the Stamp Duty Calculator. These checks do not replace a bank legal opinion, but they reduce last-minute shocks.
Why Banks Hold Back Final Disbursement Until Registration: the Practical Reason
Most buyers think the bank is being difficult. In our experience, banks are usually protecting three things: their security, the buyer’s title, and the loan documentation trail. If any one of these is weak, the bank’s recovery rights can become messy later.
Take a resale flat in Manikonda under Gandipet mandal. The seller may have an existing loan with another bank. Your bank may release part of the money to close that loan, collect the original documents, and then ask for registration. But the final amount may be released only after the registered sale deed is submitted and the earlier lender’s charge is cleared or properly tracked.
Now take a plot near Adibatla in Ibrahimpatnam mandal. Even if the buyer has paid an advance, the bank may wait for registration because land title often needs closer checking: survey number, layout approval, land use, access road, and whether any government restriction exists. For land, the bank’s legal team may insist on a fresh EC after registration before releasing the final balance.
For under-construction flats in Financial District, Kokapet or Tellapur, the final amount may depend on builder demand letters, stage of construction, tripartite agreement terms and RERA details. You can cross-check the project through the RERA Project Lookup before trusting a demand schedule blindly.
The Registration Gap: What Can Go Wrong Between Sanction and Sale Deed
The gap between loan sanction and registered sale deed is small in time, but big in legal risk. A bank sanction letter means the borrower is eligible based on income, credit and initial property review. It does not mean the bank has accepted every future risk without conditions.
Here are common issues that banks try to avoid:
- Mismatch in names: Seller name in old deed, Aadhaar, PAN, EC and current draft sale deed may not match cleanly.
- Wrong schedule of property: Flat number, undivided share, survey number, extent or boundaries may be typed incorrectly.
- Pending charge: Another bank’s mortgage may still show in CERSAI or EC.
- Market value issue: The SRO market value may not support the declared structure in the deed, or stamp duty may be wrongly calculated.
- Prohibited property risk: The property may fall under a restriction list or need deeper checking under Section 22-A.
- Builder or society dues: For resale flats, unpaid maintenance, corpus, transfer charges or NOC issues may delay handover of originals.
In Telangana, Section 22-A risk is not a small topic. As per latest IGRS data in our database, there are 3,076,153 prohibited property entries under Section 22-A. That figure alone explains why banks do not take land title casually. Before committing to a plot or old house, check the Section 22-A Prohibited Property Check and then still get the property legally verified.
How the Bank Usually Structures Final Disbursement
Different banks follow different internal processes, but the broad pattern is similar. The bank may first approve your loan, then issue a sanction letter, then complete legal and technical verification, then prepare loan documents, and then disburse according to the transaction type.
| Transaction type | What the bank checks | Why final amount may wait |
|---|---|---|
| Resale flat in areas like Kukatpally, Miyapur or Kondapur | Original sale deed, link documents, EC, society NOC, existing loan closure | Bank wants registered sale deed and control of original documents |
| Builder flat in Gachibowli, Kokapet or Tellapur | RERA, approvals, construction stage, builder demand, tripartite terms | Disbursement follows construction or registration conditions |
| Open plot in Shankarpally, Mokila or Ghatkesar | Survey number, layout approval, land use, road access, title chain | Land must be registered and mortgageable without restriction |
| Independent house in Uppal, LB Nagar or Alwal | Land title, building approval, property tax, EC, boundaries | Bank checks both land and building security |
The key point is simple: the bank wants the transaction to close in a way that gives it a valid mortgage. If the final disbursement is made too early and registration fails, the bank has released money without complete security. No prudent lender wants that situation.
Registration Office Reality: Buyer, Seller and Banker Must Be Aligned
At Telangana SRO offices, the practical coordination matters as much as the legal paperwork. The buyer brings margin money. The bank brings loan disbursement instructions. The seller expects full payment. The sub-registrar registers only based on proper documents and fee payment. If one piece is missing, the day becomes stressful.
Before booking the slot, confirm which SRO has jurisdiction. A property in Narsingi may not fall where a first-time buyer assumes. A plot near Patancheru, a flat in Nallagandla, and a villa in Kollur can fall under different registration arrangements depending on village and jurisdiction. Use the Find Your SRO Office or SRO Village Directory before you prepare the deed.
For land parcels, do not rely only on a layout marketing brochure. Match the survey number, village, mandal and extent. The Survey Number Finder helps you start that check. If you are unsure about records, run a wider check through the Property Verification Tool.
Many buyers also forget that the bank’s disbursement mode may not be a casual bank transfer. It may be a demand draft, banker’s cheque, direct credit to seller, payment to an existing lender, or split payment. If there is an existing loan, your bank may first pay the old lender, collect original documents, and then clear the seller’s remaining amount. That is normal, but it must be written clearly in the disbursement plan.
Why EC and CERSAI Matter After Registration
The Encumbrance Certificate is not just a formality. It shows registered transactions affecting the property for the period searched. Banks use EC to see whether the seller’s title is clean, whether previous mortgages were released, and whether the buyer’s sale deed has appeared after registration.
CERSAI is another layer. It records security interests created by lenders. If the property already has a charge, the new bank wants to know how that charge will be closed. If the buyer’s bank is creating a new mortgage, it must complete its own reporting process after registration and loan documentation.
For buyers, this is where patience helps. A bank officer asking for a post-registration EC is not necessarily delaying you for fun. They are checking whether the document has been registered correctly and whether any earlier mortgage or claim is still visible. Use the EC Analyzer to understand entries better, and use the CERSAI Charge Check if there is any doubt about an existing loan.
What Buyers Should Confirm Before the Registration Day
Here is the checklist I would personally insist on before walking into the SRO for a bank-funded purchase in Hyderabad or nearby districts:
- Read the sanction letter conditions: Some sanctions clearly say final disbursement is subject to registration, original documents and mortgage creation.
- Get bank disbursement wording in writing: Ask whether the final amount comes before registration, at registration, or after submission of registered deed.
- Confirm seller acceptance: The seller must know the bank’s process. Do not reveal it at the SRO counter.
- Check EC before deed execution: A fresh EC search reduces risk of hidden recent transactions.
- Verify Section 22-A status: Especially for plots, old houses and land parcels in village limits.
- Match draft deed with bank legal report: Flat number, extent, UDS, boundaries, survey number, village and mandal should match.
- Confirm stamp duty and market value: Use SRO-ready values, not broker assumptions.
- Keep margin money ready: Banks usually do not fund the full transaction cost, and registration charges must be planned separately.
- Ask about original document custody: After registration, the bank normally takes custody of the original sale deed for a mortgaged property.
If the property has a building component, use the Building Value Calculator to understand construction value assumptions. For apartments with land share and construction value split, the Composite Value Calculator can be useful while reviewing the transaction structure.
Seller Anxiety Is Real — Handle It Beforehand
Sellers often get nervous when they hear that the bank will release some amount after registration. Their fear is understandable: once they sign the sale deed, ownership moves to the buyer, so why should they wait for payment?
The answer lies in documentation. A good banker will issue a clear disbursement letter or payment arrangement showing how and when funds will move. In resale cases, the seller can ask for confirmation that the bank has sanctioned the loan, completed legal checks, and approved the disbursement subject only to registration formalities.
Where we see disputes is when buyers are casual. They tell the seller, “loan is approved”, but they do not explain the bank’s last-mile process. Then on registration day, the seller refuses to sign unless the full money is already credited. That is avoidable. Have one meeting with the seller, buyer, banker and document writer before the slot is booked. Put payment flow in writing.
Local Examples from Hyderabad’s Active Corridors
In Kokapet and Financial District, many transactions are builder-led, so banks are used to project approvals, RERA checks and stage-wise disbursement. In older resale markets like Ameerpet, Himayatnagar, Mehdipatnam and Secunderabad, banks spend more time on link documents and old EC entries. In Tellapur and Nallagandla, apartment transactions often involve builder NOCs and handover letters. In Mokila, Shankarpally and Ghatkesar, land title and layout approval become more sensitive.
That is why there is no one fixed answer for every property. The same bank may behave differently for a ready flat in a well-known gated community and a plotted land deal in a developing village. That is not bias; it is risk reading.
Government market value also varies by locality, property type and classification. Do not depend on a WhatsApp rate sheet or a broker’s round figure. Check the value applicable to your property category through official registration data or tools before preparing the sale deed. A wrong value can disturb stamp duty calculations and bank paperwork.
When Should You Worry?
A post-registration final disbursement condition is normal. But some situations deserve caution.
- The bank has not completed legal verification even on the registration day.
- The seller has an existing loan, but there is no clear closure letter or document release plan.
- The EC shows old transactions that nobody can explain.
- The property appears in a prohibited or disputed category.
- The draft sale deed differs from the bank-approved property schedule.
- The builder is asking for payment outside the recorded demand or agreement terms.
If any of these happen, pause. Do not let social pressure at the SRO push you into signing. Registration is not a small formality; it is the legal transfer itself.
Our View: Final Disbursement After Registration Is Sensible, If Transparent
I do not see final disbursement holdback as a problem by itself. In fact, it can protect the buyer too. If the bank insists on a clean registered deed, updated EC and proper mortgage creation, it is indirectly forcing discipline into the transaction.
The problem is poor communication. Buyers should not discover the bank’s condition while standing near the biometric desk. Sellers should not hear about deferred payment after signing the document. Bankers should not speak in half-sentences. A property transaction in Telangana already has enough moving parts — SRO, EC, challans, market value, pahani or revenue history, builder documents, CERSAI and loan agreements. Clarity saves the day.
Before you fix your registration date, ask one blunt question to your banker: “What exact documents do you need before releasing the final amount, and when will the seller receive it?” Get that answer in writing. That one step can prevent a full-day mess at the SRO.
Frequently Asked Questions
Why do banks hold back final disbursement until registration?
Banks hold back the final amount because they need proof that the property is registered in the borrower’s name and can be mortgaged properly. The registered sale deed, EC and original documents help the bank secure its loan.
Can the seller refuse registration if the bank releases money after registration?
Yes, a seller may refuse if the payment flow was not agreed earlier. The buyer should get the bank’s disbursement plan in writing and explain it to the seller before booking the SRO slot.
Is post-registration disbursement common for resale flats in Hyderabad?
Yes, it is common in many resale cases, especially where the bank wants the registered sale deed, fresh EC, original documents or closure proof of an earlier loan before releasing the last amount.
What should I check before registration in Telangana?
Check EC, Section 22-A status, SRO jurisdiction, market value, draft sale deed details, seller title, existing bank loan closure and the bank’s final disbursement conditions.
Does a loan sanction letter mean the full amount is ready?
No. A sanction letter means the bank has approved the loan subject to conditions. Final disbursement depends on legal, technical, documentation and registration requirements.