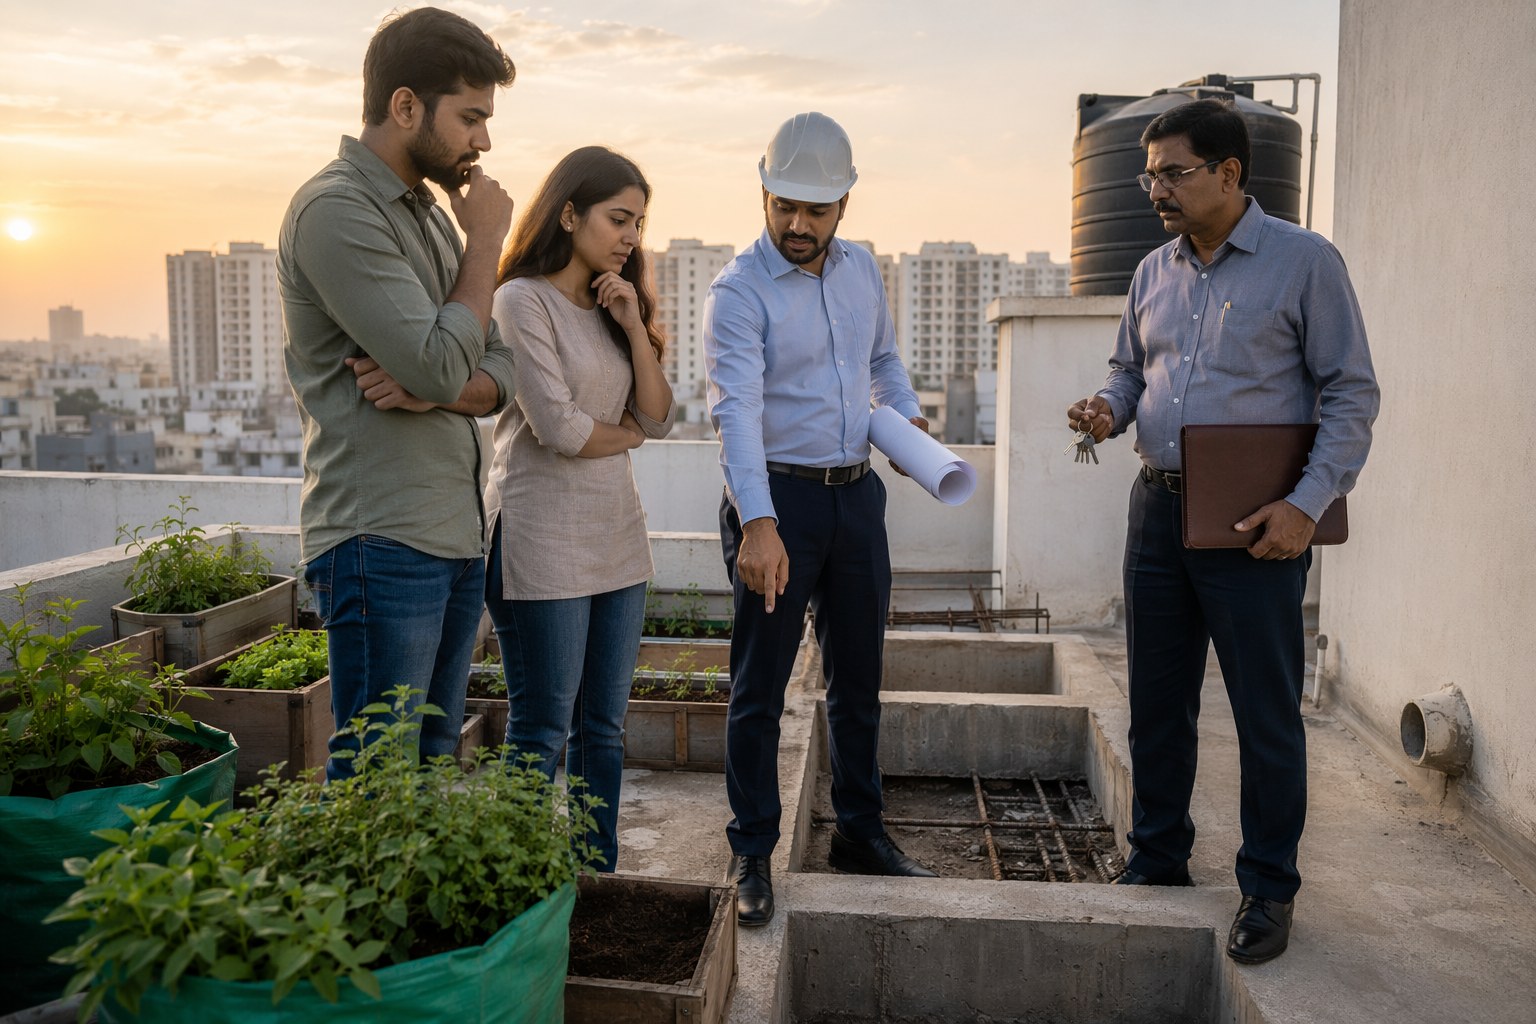
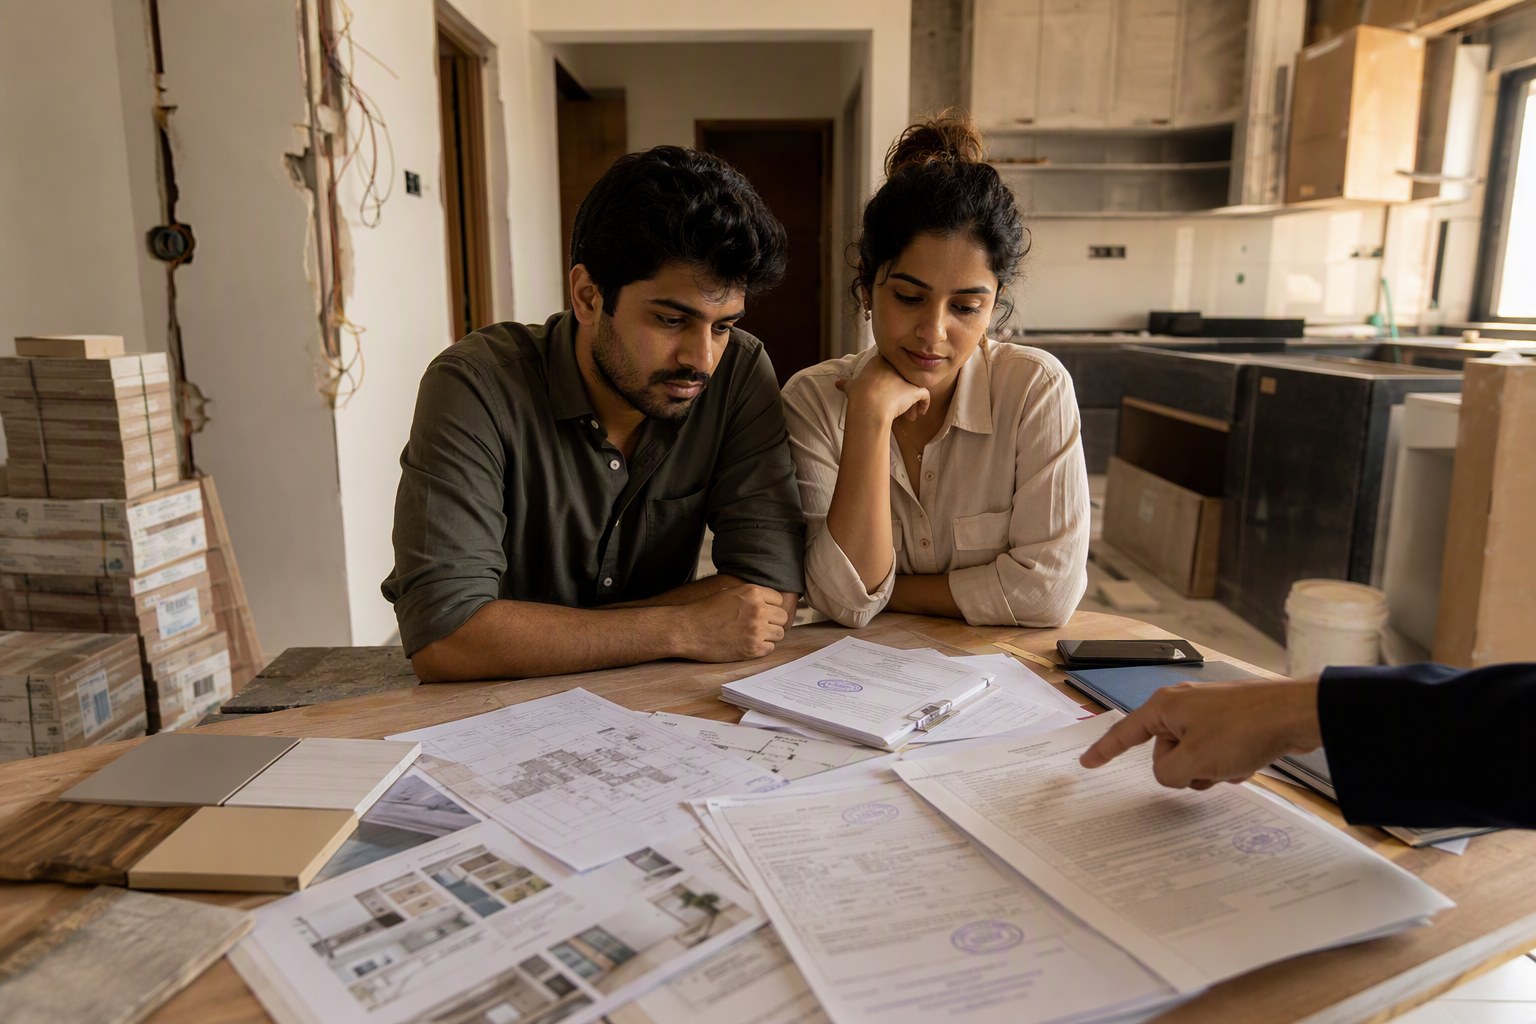
Top-Up Home Loan for Renovation sounds simple after registration: take some extra money from the same bank, finish modular kitchen, wardrobes, false ceiling and bathroom upgrades, then move in peacefully. That is what a young Hyderabad buyer from Kondapur thought after purchasing a resale flat near Botanical Garden. The sale deed was done, keys were in hand, and the interior contractor was ready. Then the bank asked for fresh income papers, updated property checks, title comfort, EC, CERSAI, and a closer look at the link documents. The loan was not rejected on day one, but the buyer suddenly realised that a top-up is not an ATM attached to the old home loan.
We’ve seen this story often in Serilingampally, Narsingi, Manikonda, Miyapur, Uppal, Kompally and LB Nagar. Buyers stretch themselves for the purchase, assuming the interiors can be funded later through a top-up. That plan can work, but only when the borrower and the property both still look clean to the lender.
A top-up loan is granted on fresh comfort, not old sentiment. The bank may already know you, but it will still recheck your repayment ability and property documents.
Top-Up Home Loan for Renovation: Why Banks Recheck Your File
A home loan sanction is linked to a specific transaction at a specific time. Once the sale deed is registered and the original documents are deposited with the lender, many borrowers assume the bank has already accepted everything forever. That is not how credit teams work.
For a Top-Up Home Loan for Renovation, the lender normally looks at three things again:
- Fresh eligibility: Your present salary, business income, EMIs, credit behaviour and job stability.
- Property comfort: Whether the title, registration trail, EC and local records still satisfy the bank’s risk team.
- Loan-to-value comfort: Whether the property value and outstanding loan leave room for a top-up as per the lender’s internal rules.
The buyer in our Kondapur story had no issue with intention. He wanted practical interiors after purchase. But his credit card usage had gone up after registration, and one older personal loan was still running. The bank asked for fresh salary slips and bank statements. Then the legal team sought an updated Encumbrance Certificate because the resale flat had multiple past owners. That is where the waiting started.
In Hyderabad resale deals, especially in older apartment pockets like Ameerpet, Kukatpally, Chandanagar, Mehdipatnam and Dilsukhnagar, banks can be stricter on link documents. If the original builder sale deed, development agreement, GPA trail, partition deed or prior sale deed is missing or unclear, a top-up can get delayed even when the first loan was sanctioned earlier.
The Renovation Plan Usually Starts After Registration
Most families don’t do full interiors before registration. They first complete the sale, then plan carpentry, lights, kitchen, civil changes and appliance upgrades. In gated communities around Gachibowli, Tellapur, Kokapet and Nallagandla, buyers often block an interior vendor even before the loan disbursement is complete. In standalone apartments in Peerzadiguda, Boduppal, Nagole and Alwal, buyers may prefer a local carpenter and do work in stages.
The timing creates the catch. By the time the buyer asks for a top-up, the bank may say, “Give us updated papers.” This includes personal financials and property papers. If the buyer has changed job, taken a car loan, delayed any EMI, or if the property has some document gap, the top-up may not move as quickly as expected.
In our experience, the safer approach is to discuss renovation funding before closing the purchase. Not because you should borrow blindly, but because you should know whether the same bank is likely to support a top-up soon after registration. Some lenders prefer a repayment track record before considering a top-up. Some may ask for a fresh valuation. Some may treat interior funding differently from a generic top-up.
Top-Up Home Loan for Renovation: Documents Lenders Ask For
Every lender has its own checklist, but Hyderabad borrowers usually face a familiar set of requirements. If you are planning a Top-Up Home Loan for Renovation, keep these ready before calling the relationship manager.
| Document area | What the bank may ask | Why it matters |
|---|---|---|
| Income papers | Latest salary slips, bank statements, Form 16 or ITRs, business financials if self-employed | To confirm fresh repayment capacity |
| Loan behaviour | Existing EMI details, credit report review, repayment track | To see whether new borrowing is safe |
| Property title | Sale deed, link documents, mother deed, prior registrations, builder documents if applicable | To confirm ownership chain and legal comfort |
| Encumbrance check | Updated EC from the relevant SRO period | To verify registered charges, sales or claims |
| Mortgage charge | CERSAI record check | To verify existing security interest on the property |
| Local records | Mutation, property tax, approved plan, occupancy-related papers where relevant | To support property identity and compliance |
| Renovation purpose | Interior estimate, contractor quote or renovation plan if requested | To understand end use of funds |
Before applying, you can do a basic document hygiene check using Encumbrance Certificate Search, CERSAI Charge Check and Property Verification Tool. These tools do not replace a bank lawyer, but they help you spot issues before the file gets stuck.
The Title Comfort Problem: Why a Small Gap Can Delay a Big Plan
Hyderabad buyers often underestimate title comfort. The sale deed may be registered, but the bank’s legal team may still ask questions when a fresh top-up file opens. A resale flat in Manikonda may have a development agreement from the landowner, a supplementary agreement, a builder sale deed, then two resale deeds. A villa in Mokila or Kollur may have land conversion records, layout approvals and panchayat-era papers. A plot-side construction in Moinabad or Shankarpally may require survey number clarity and revenue record comfort.
If one link document is unreadable, unstamped in the expected way, not traceable, or not matching the present schedule, the lender may not be comfortable. For apartments, the undivided share of land must match the chain. For independent houses, boundaries, plot number, survey number, door number and municipal details should not conflict. For older properties, SRO indexing errors can create confusion.
One very common issue is name mismatch. A person’s initials in an old sale deed, Aadhaar style name in the new deed, and bank statement name may not be exactly the same. It may look minor to the family, but legal and credit teams work on paper trail. If the bank asks for an affidavit, clarification deed or supporting proof, the top-up timeline stretches.
For land and plot-related checks, tools like Survey Number Finder, Find Your SRO Office and SRO Village Directory are useful starting points, especially when the property falls near mandal or SRO boundary confusion.
Section 22-A Check: The One Search Buyers Should Not Ignore
Telangana has a large prohibited properties dataset under Section 22-A. As per the verified database available with us, prohibited properties records stand at 3,076,153. This number alone should make every buyer cautious before assuming that registration means every future bank process will be easy.
Section 22-A entries may relate to government land, assigned land, endowment land, wakf-related entries, court-affected records or other restricted categories as reflected in government records. For a normal apartment in a well-known project, the risk may be low, but banks still prefer clarity. For plots, farm land, peripheral gram panchayat layouts and older revenue conversions, the check becomes even more relevant.
If your property is in mandals like Gandipet, Shankarpally, Moinabad, Maheshwaram, Hayathnagar, Keesara, Medchal, Ghatkesar or Ibrahimpatnam, don’t rely only on broker confidence. Run a check through Section 22-A Prohibited Property Check. If the survey number, village or schedule creates doubt, resolve it before planning a renovation loan.
Eligibility Can Change Between Purchase and Top-Up
Many buyers treat top-up eligibility as a continuation of the original home loan. Banks don’t. They assess present cash flow. That means your position after registration matters more than your position at sanction time.
Here are situations where a top-up request may become weaker:
- You used credit cards heavily for stamp duty, shifting, appliances or advance interiors.
- You took a personal loan after the home loan was sanctioned.
- Your co-applicant changed job or stopped earning.
- Your business bank statements show lower turnover than before.
- You missed or delayed any EMI, even outside the home loan.
- Your property valuation does not support the top-up amount sought.
For salaried buyers in HITEC City, Financial District or Pocharam IT corridors, lenders may be comfortable if salary credits are stable. For self-employed buyers in Begum Bazar, Ranigunj, Kukatpally, Attapur or Uppal industrial belts, bank statements and GST-linked cash flow may be examined more closely. The property is the security, but repayment comes from income. Banks never forget that.
Guideline Value, Market Value and the Bank’s Internal Valuation
Another confusion is value. Borrowers ask, “My flat is in Kokapet, prices have moved up, why not give top-up?” The lender may not simply accept neighbourhood talk. It may consider registered value, government guideline value, internal valuation report, project quality, age of property and saleability.
Government guideline value is not always the same as market value. In some localities, resale asking prices can be much higher than the value used for registration. In other pockets, old records and present market conditions may not match neatly. Before assuming a large top-up, check the government value through Market Value / Guideline Value Search. If you are still at purchase planning stage, use Stamp Duty Calculator to understand registration cost impact, because many buyers eat into their renovation budget at this stage itself.
For flats where land share and built-up value need a clearer reading, Composite Value Calculator can help you think through the value components. Again, the bank’s valuer has the final say for lending, but an informed borrower asks better questions.
What Happened to the Kondapur Buyer?
The Kondapur buyer did get the top-up, but not in the quick way he had imagined. The bank asked for an updated EC, a CERSAI confirmation, fresh salary documents, and clarification on one earlier link deed where the flat number format differed between two documents. The interior contractor had to wait. The family moved in with basic work first and completed wardrobes later.
There was no dramatic fraud. No court case. No hidden villain. Just paperwork. That is exactly why this topic matters. Renovation dreams are emotional, but top-up loans are processed by people who read documents line by line.
My view is simple: if you plan interiors through borrowing, treat it as part of the home-buying file from day one. Don’t wait until the carpenter is standing in the living room with measurements.
How to Prepare Before Applying for a Top-Up Home Loan for Renovation
A smart borrower does not submit a half-ready file and then chase the bank daily. Prepare first, then apply.
1. Keep a clean post-purchase cash trail
After registration, avoid unnecessary unsecured borrowing if you plan to ask for a top-up soon. Maintain salary credits, EMI discipline and clear bank statements. If you are self-employed, keep business and personal transactions understandable.
2. Download an updated EC
Even if the bank has your original sale deed, an updated Encumbrance Certificate helps confirm the registration trail after purchase. Use Encumbrance Certificate Search and review whether the latest sale deed is reflected correctly.
3. Check CERSAI
If the property is already mortgaged to your lender, the security interest should be properly recorded. A CERSAI Charge Check can help you see whether there are charge-related entries needing explanation.
4. Verify property identity
For plots and independent houses, check survey number, village, mandal, SRO and schedule details. In areas like Bachupally, Dundigal, Adibatla, Tukkuguda and Shamshabad, boundary and jurisdiction clarity can save time.
5. Keep renovation estimates realistic
If the bank asks for end-use proof, give a proper estimate from the contractor. Don’t submit vague handwritten amounts. A clear scope of work gives confidence, especially when the top-up is specifically for renovation.
6. Speak to the existing lender first
Your current home loan lender already holds the original documents. That can make the process smoother than going to a new lender. But if their terms are not suitable, understand foreclosure, takeover and fresh legal verification requirements before shifting.
When a Personal Loan May Look Easier, But Cost More in Stress
Many borrowers switch to a personal loan when the top-up takes time. It is faster in many cases, but it can increase EMI pressure. Since we are not comparing live bank rates here, I won’t throw random percentages. The practical point is this: unsecured loans are usually assessed differently from home loan top-ups, and the repayment burden can affect your household cash flow.
If the renovation is urgent, split the work. Do safety, plumbing, electrical and essential carpentry first. Decorative work can wait. Hyderabad homeowners sometimes finish the entire flat before moving in because of social pressure. That pressure is not worth a strained EMI cycle.
Red Flags That Can Affect a Renovation Top-Up
Watch these issues before applying:
- Old link documents missing from the resale file.
- Mismatch in flat number, plot number, survey number or boundaries.
- Property tax records not updated after purchase.
- Mutation or municipal records still in the previous owner’s name.
- Any Section 22-A doubt in land-linked properties.
- Unclear builder approvals or occupancy-related papers.
- Multiple loans or charges appearing in records.
- Recent credit score damage due to delayed payments.
None of these automatically means the top-up will fail. But each one can trigger more questions. Bank legal teams prefer clean answers, not verbal assurances.
Final Word from the Ground
A Top-Up Home Loan for Renovation is a useful product for Hyderabad homeowners, especially after a heavy purchase outflow. But it is not automatic. The bank checks you again and checks the property again. That is fair from a lending point of view.
If you are buying in Narsingi, Kondapur, Miyapur, Uppal, Tellapur, Kompally or any fast-moving Telangana market, plan the renovation loan before registration. Keep your EC, title chain, SRO details, CERSAI record and income papers ready. The family may be dreaming of a perfect kitchen, but the bank is looking for a perfect file.
Frequently Asked Questions
Can I take a Top-Up Home Loan for Renovation immediately after buying a flat?
It depends on the lender. Some banks may consider it after checking fresh eligibility, property valuation and documents. Others may prefer a repayment track record before approving a top-up.
Will the bank recheck property documents for a renovation top-up?
Yes. Even if the same bank gave the original home loan, it may ask for updated EC, title papers, CERSAI details, valuation and other property checks before approving the top-up.
Is Section 22-A check needed for an apartment top-up loan?
For many regular apartments, the risk may be lower, but land title still sits behind the project. For plots, villas and peripheral properties, Section 22-A checking is especially useful before applying.
Can poor credit card usage affect my top-up home loan?
Yes. High credit card dues, new personal loans or delayed payments can reduce fresh eligibility. Banks look at your current repayment capacity, not only your original home loan sanction.
Which tools can help before applying for a renovation top-up?
Start with Encumbrance Certificate Search, CERSAI Charge Check, Section 22-A Prohibited Property Check, Guideline Value Search and Property Verification Tool. These help you identify document gaps early.