Telangana Home Loan Pre-Approval sounds like a green signal, and for many Hyderabad buyers it feels exactly like that. Rohit, a software professional working near Financial District, got a pre-approval SMS from his bank for ₹95 lakh. The banker said his income, CIBIL score, repayment capacity and existing obligations looked fine. That same weekend, he visited a 2BHK resale flat near Narsingi, Gandipet mandal, liked the view, negotiated hard, and paid ₹2 lakh as token money.
Then the real story started.
When the bank’s legal team checked the property file, they asked for a fresh encumbrance certificate, link documents, occupancy certificate, sanctioned plan, and society NOC. One old mortgage entry in the EC had not been properly closed. The seller said, “Sir, loan approval already came no?” Rohit learnt the hard way that pre-approval is only a financial comfort. It is not a property clearance, not a title certificate, not a Section 22-A check, and not a promise that the bank will fund that exact flat.
In our experience, the biggest confusion in Hyderabad home buying is this: buyers treat loan pre-approval as property approval. Banks don’t see it that way.
Telangana Home Loan Pre-Approval is about you, not the property
A home loan pre-approval tells you that the bank is broadly comfortable with your repayment capacity. It checks your salary credits, age, employer profile, credit score, existing EMIs and sometimes your bank statements. It does not mean the flat in Narsingi, villa in Tellapur, plot in Adibatla or resale apartment in Miyapur is legally safe.
That difference matters because Telangana property documents can be layered. A resale flat may have older link documents from 2008. An open plot may have survey number mismatch between sale deed and pahani. A villa project may have HMDA approval but still need careful layout verification. A gated community apartment may have RERA registration, but a buyer still has to check tower-wise approvals, carpet area, promised amenities and possession status.
Before paying token money, buyers should run basic checks. Start with the Encumbrance Certificate Search for mortgage and transaction history. Check government market value through the Market Value / Guideline Value Search. If it is land or a plot, verify the survey details using the Survey Number Finder. For projects, use the RERA Project Lookup. These are not decorative steps. They can save you from losing advance money.
Why Telangana Home Loan Pre-Approval still makes buyers pause
One would think pre-approval gives confidence. It does, but only up to a point. Serious buyers still pause because they know the final loan sanction depends on property-level checks. Banks can reduce the loan amount, ask for more margin money, delay disbursement, or reject the property even after pre-approval.
We’ve seen this in Kokapet, Manikonda, Bachupally, Kompally, Uppal, LB Nagar and Shamshabad. The buyer’s income is fine. The flat is attractive. The price looks okay. But one missing occupancy certificate, one unclear link document, one pending mortgage closure, or one mismatch in land extent can slow down the file.
In Telangana, this pause has another reason: prohibited property risk. As per the available database fact, there are 147,934 prohibited properties under Section 22-A. That number is not small. It tells us that buyers must not assume every land parcel is freely transferable just because a seller has a photocopy of an old sale deed.
If you are considering land in Shankarpally mandal, Maheshwaram mandal, Patancheru mandal, Shamshabad mandal or Yacharam mandal, do not skip the Section 22-A Prohibited Property Check. Banks also become cautious when revenue records, Dharani entries, and registration records do not speak the same language.
Telangana Home Loan Pre-Approval versus final sanction
Here is the clean way to understand the difference. Pre-approval is like the bank saying, “You look eligible.” Final sanction is the bank saying, “You, this property, and this transaction are acceptable.” That second sentence needs much more work.
| Stage | What is checked | What it does not prove |
|---|---|---|
| Pre-approval | Your income, CIBIL score, age, job profile and broad EMI capacity | It does not prove title, approvals, RERA status or marketability of the property |
| Legal verification | Sale deed, link documents, EC, mutation, society papers, permissions and ownership chain | It does not confirm your final EMI comfort if interest rate or tenure changes |
| Technical valuation | Property condition, approved plan, area, stage of construction, valuation and location | It may not match the seller’s expected price |
| Final sanction and disbursement | Borrower eligibility plus property acceptability plus agreement terms | It still depends on documentation and payment schedule |
This is why a buyer with ₹1 crore pre-approval may not get ₹1 crore disbursement for every property. If the bank’s valuer estimates lower value, the eligible loan may drop. If the project is not on the bank’s approved list, the file may go for deeper legal review. If the seller has an active loan, the buyer’s bank may insist on a proper loan closure process and original document release.
The Hyderabad token money trap
Token money is where many buyers get emotionally locked. The seller says three other buyers are waiting. The broker says the owner is travelling tomorrow. The buyer has a pre-approval letter and feels safe. So the money moves quickly.
But token terms are often vague. Some receipts simply say “advance received for flat purchase” without mentioning refund conditions. If the bank rejects the property, who bears the risk? If EC shows an old charge, does the seller have time to clear it? If RERA details do not match the brochure, can the buyer step back? These points should be written before payment.
For a ₹90 lakh apartment in Gachibowli or Kondapur, Telangana registration costs are not minor either. For a normal sale deed, buyers commonly calculate around 6% total government charges, including stamp duty, transfer duty and registration fee, subject to property type and rules applicable at the time of registration. Use the Stamp Duty Calculator before finalising your budget. Many first-time buyers remember the down payment but forget stamp duty, interiors, GST where applicable, maintenance corpus and moving costs.
What banks usually check after pre-approval
Different banks and housing finance companies have their own formats, but the broad checklist is similar across Hyderabad, Rangareddy, Medchal-Malkajgiri and Sangareddy districts.
1. Title and link documents
The bank’s legal panel will ask how the current owner got the property. For resale flats, they check the current sale deed, earlier sale deeds, gift deed or partition deed if any, link documents and sometimes parent documents. If one link is missing, the bank may ask for certified copies from the SRO.
2. Encumbrance certificate
The EC shows registered transactions and charges for a chosen period. It is not a perfect title guarantee, but it is one of the first documents banks check. A buyer should independently pull an EC, not only rely on what the seller sends on WhatsApp.
3. Building approval and occupancy certificate
For apartments, banks look at sanctioned plan, building permission, occupancy certificate or completion certificate depending on the case. In areas under GHMC, HMDA and municipal limits, approval records can decide whether a lender is comfortable.
4. RERA registration
For eligible ongoing projects, RERA details matter. Buyers should verify promoter name, project name, land extent, completion date, approvals, and any changes. A project being advertised heavily on ORR access, metro hopes or lake view does not replace RERA verification.
5. Valuation and technical report
The bank valuer checks location, built-up area, condition, marketability, construction stage and approved usage. A seller may quote ₹11,000 per sq ft in a premium pocket of Kokapet, while the bank may fund based on a lower internal valuation. That gap becomes buyer’s margin money.
Where property checks become more sensitive in Telangana
Every locality has its own risk pattern. In core resale markets like Himayatnagar, Ameerpet, SR Nagar and Begumpet, old apartment records and redevelopment discussions can complicate title review. In fast-growing western corridors like Narsingi, Puppalaguda, Tellapur and Kollur, buyers must check approvals, access roads, and project commitments. In plot-heavy belts like Shadnagar, Yadagirigutta, Maheshwaram and Ibrahimpatnam, survey numbers, layout approval, land use and Section 22-A status become critical.
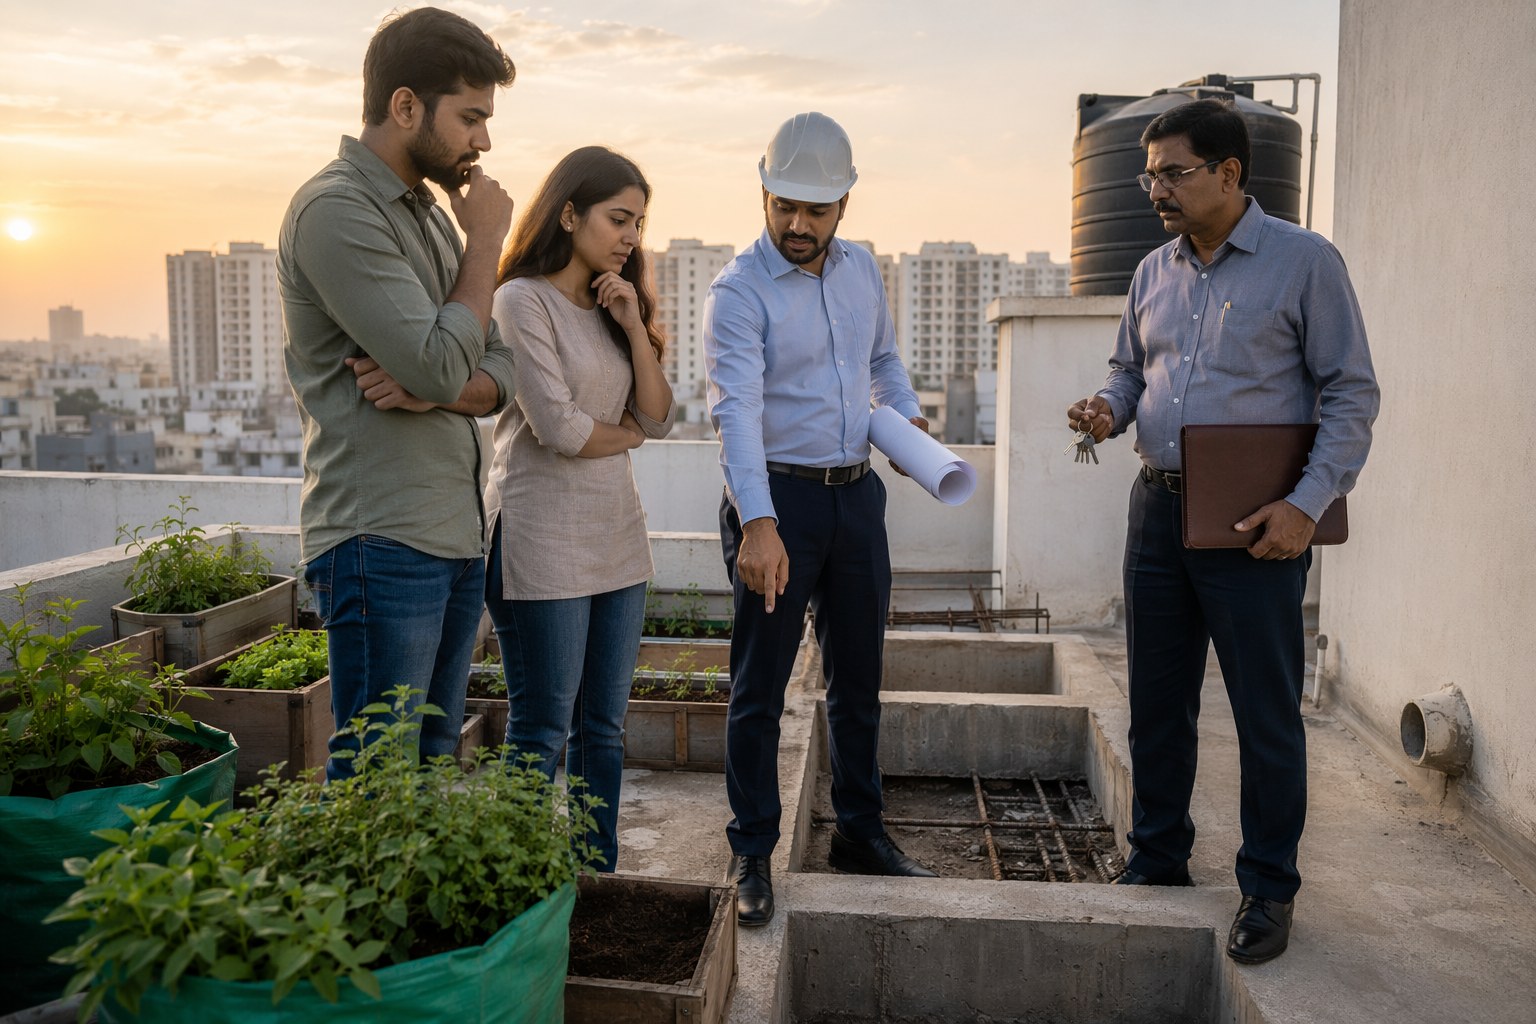
Open plots need extra attention because land records in Telangana may involve pahani, mutation, Dharani entries, old pattadar passbooks, court cases, assigned land issues or government land boundaries. A bank may be happy with your salary but still refuse funding if land title is not clean.
Use the Land Use Zone Finder if you are buying land for a future house or investment. For a constructed property, the Road Width Check can also matter because access road width affects permissions, valuation and future development potential.
A practical sequence before paying advance
If Rohit had asked us before paying token money, we would have suggested a simple order. It is not slow. It is sensible.
- First, get your Telangana Home Loan Pre-Approval so you know your broad budget and EMI comfort.
- Second, shortlist only properties with basic documents ready: sale deed, link documents, EC, tax receipts, approvals, OC where applicable, and seller identity proof.
- Third, check EC and market value through public tools before negotiation becomes emotional.
- Fourth, verify RERA for projects and compare project details with the brochure and agreement draft.
- Fifth, check Section 22-A risk for land and plots, especially in expanding mandals and peri-urban villages.
- Sixth, write token money terms clearly, including refund if legal or bank verification fails.
- Seventh, identify the correct SRO using the Find Your SRO Office tool before planning registration logistics.
This order reduces pressure. It also gives you negotiation strength. If the seller’s documents are clean, they usually cooperate. If they keep saying “everything is there” but do not share papers, that itself is a signal.
Pre-approval can still be useful if you treat it correctly
I am not against pre-approval. In fact, serious buyers should get it before house hunting. It prevents unrealistic searching. A buyer with ₹70 lakh loan comfort should not waste three months chasing ₹1.5 crore villas near Osman Nagar unless there is family funding. Pre-approval also helps when negotiating with sellers because it shows intent.
But pre-approval must be treated like the first gate, not the finish line. The second gate is property verification. The third gate is agreement review. The fourth gate is final sanction and disbursement.
Hyderabad buyers often move fast because prices in preferred pockets can change quickly. We understand that anxiety. In markets like Financial District, Kondapur, Tellapur and Kollur, good inventory does get picked up. Still, one week of document checking is cheaper than one year of legal headache.
What to write in the sale agreement after pre-approval
Your agreement or advance receipt should protect both sides. It should mention the property details, flat number, survey number where relevant, total sale consideration, payment schedule, loan dependency, document handover timeline, and refund conditions.
For resale property, add a clause that the transaction is subject to satisfactory legal verification by the buyer’s advocate or lending bank. If the seller has an existing loan, mention how closure will happen and who will collect the original documents. For an under-construction project, align payments with construction stage and RERA disclosures, not only verbal promises.
Do not leave these points for later. Once emotions enter, documentation becomes difficult. A polite but firm written clause is better than ten phone calls after a problem appears.
Final view from the Hyderabad market
Telangana Home Loan Pre-Approval is a good financial starting point. It tells you what you can afford. It does not tell you whether a property is clean, registrable, approved, correctly valued or safe from future disputes.
Rohit eventually got his token money back, but only after three uncomfortable weeks. The seller cleared the old mortgage entry later, and another buyer purchased the flat. Rohit moved to a different apartment in Nanakramguda after doing EC, RERA and society checks first. His lesson was simple: bank comfort on borrower is not bank comfort on property.
That is the pause buyers feel even after pre-approval. It is not fear. It is maturity. In Telangana real estate, the smartest buyer is not the one who gets the fastest loan message. It is the one who verifies before committing money.
Frequently Asked Questions
Does Telangana Home Loan Pre-Approval mean my property is approved?
No. It mainly checks your repayment capacity. The bank will separately verify the property title, approvals, EC, valuation and other documents before final sanction.
Can a bank reject a property after giving pre-approval?
Yes. If legal title is unclear, approvals are missing, valuation is lower, EC has unresolved entries, or the property falls under restrictions, the bank can reject or reduce funding.
Should I pay token money after getting pre-approval?
Pay only after checking basic documents and writing refund conditions. The receipt should say what happens if bank legal verification or property checks fail.
Which checks should I do before buying a plot in Telangana?
Check survey number, Dharani and pahani details, EC, layout approval, land use, SRO records and Section 22-A prohibited property status before paying advance.
How much should I budget beyond down payment?
Budget for stamp duty, transfer duty, registration fee, interiors, maintenance corpus, legal checks and moving costs. For many normal sale deeds in Telangana, buyers commonly estimate around 6% towards government registration charges, subject to applicable rules.